Up next in 10

Top City investment analyst on how this global stock market slump will affect YOU
Mar 9, 2026
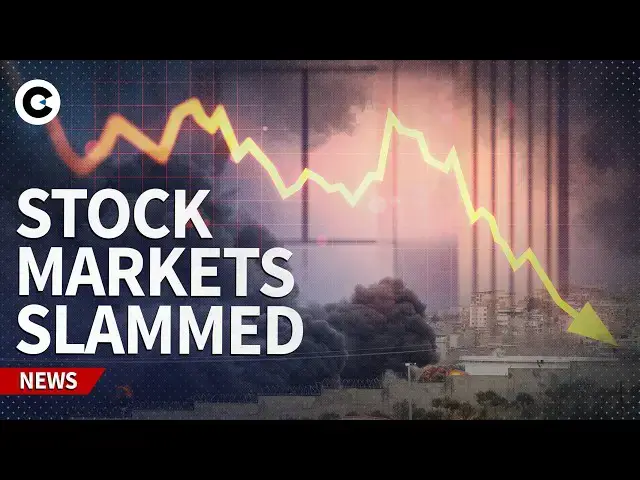
Stock markets are reeling after global economies faced warnings over what could the “biggest energy crisis” in modern history after the price of oil breached the $100 mark for the first time since the energy crisis in 2022.
Brent crude, the international benchmark for oil, surged over 25 per cent to highs of $118 per barrel as the week’s trading began in Asia – marking the commodity’s biggest one-day gain in six years.
City AM's Simon Hunt and Maisie Grice spoke to former Chief Investment Officer at Morningstar, Dan Kemp - now founder and CEO of Portfolio Thinking - to get his reaction to what this downturn could mean for investors at home.
Get more of City AM 👇
🌐 http://www.cityam.com
X(formerly Twitter): http://twitter.com/CityAM
Facebook: http://www.facebook.com/cityam
Instagram: http://www.instagram.com/city_am
LinkedIn: http://www.linkedin.com/company/cityam
Show More Show Less View Video Transcript
0:00
Markets are in turmoil as investors
0:02
weigh the scale of the fallout from the
0:04
Iran war. The oil price has rocketed
0:07
above $100 a barrel as the continued
0:09
effect of shutdown to the Strait of
0:10
Hormuz, the key waterway for the
0:12
transportation of around a fifth of the
0:14
world's oil, has renewed fears over
0:16
disruption to energy supplies.
0:19
Surging oil and gas prices are expected
0:21
to trigger a spike in inflation, causing
0:24
analysts to pare back their expectations
0:26
of interest rate cuts with some, to the
0:28
horror of mortgage holders, even
0:30
forecasting interest rate rises over the
0:33
coming months.
0:35
To help make sense of it all, I'm
0:36
delighted to say we're joined by Dan
0:39
Kemp, founder of Portfolio Thinking and
0:42
former Chief Research and Investment
0:44
Officer for Morningstar, where he
0:46
oversaw $350 billion of assets alongside
0:50
City AM's Investment Reporter, Maisie
0:52
Grace.
0:54
So, Dan, thanks ever so much for coming
0:55
in.
0:56
Um I suppose that, you know, we've seen
0:58
over a week of of of a sell-off uh in
1:01
equity markets. Um is there going to be
1:04
more of this? Have we reached the the
1:05
end of the sell-off, or is there more to
1:07
come?
1:07
>> Well, Simon, that's a really important
1:09
question, but it's exactly the wrong
1:10
question for investors to ask. Uh
1:13
because what it does encourage us to
1:14
focus on the short term, and we know
1:17
that investment is all about the long
1:19
term. And this is a really dangerous
1:20
time for investors because we see prices
1:23
moving very rapidly. We saw them move in
1:25
in one direction, uh and then they could
1:27
move back in in the other. And so, it's
1:28
it's really important to take stock of
1:30
what's happening, try and dig below the
1:32
surface news, but don't get too caught
1:35
up in the day-to-day movements. Really
1:37
focus on what uh the value is telling us
1:39
about the longer-term horizon.
1:41
>> In terms of the the rate outlook, it's
1:43
been quite staggering seeing a couple of
1:45
weeks ago what was a an expectation of a
1:47
one or two cuts later this year suddenly
1:50
reverse with with some analysts now
1:51
predicting uh Bank of England to to
1:53
raise rates uh in the next couple of
1:55
months. Uh do you give any any credence
1:58
to those projections and and how can
1:59
they transform quite so quickly?
2:01
>> Well, it's a great reminder that
2:03
economic forecasts exist to make fortune
2:05
tellers look good. Uh, that we are
2:07
constantly reminded that economic
2:10
forecasts change very rapidly and have a
2:12
terrible track record of being correct.
2:15
And so, uh, almost useless from an
2:17
investment perspective. And so, the the
2:19
bigger question, I guess, is for
2:22
individual savers and investors and
2:24
they're going to be worried about what's
2:25
happening uh, to their portfolios. Also,
2:28
what's happening to their savings and
2:30
potential interest rates as well. So,
2:31
yes, the future is not looking as rosy
2:34
as it was a few weeks ago, uh, but
2:37
remember prices haven't moved that much.
2:40
Interest rates haven't moved at all yet,
2:43
uh, and so, it's really important not to
2:45
get too het up with what the future may
2:48
hold. This is potentially a very
2:50
short-term situation. We saw that in
2:52
April last year, uh, where we had a
2:55
another big policy announcement from the
2:57
president of the US and that really blew
3:00
over quite quickly. The same thing could
3:02
happen this time.
3:03
>> You know, it's interesting what you were
3:04
saying then to Simon as well in regards
3:06
to look at the long-term cuz it's
3:07
something that analysts, commentators
3:10
sort of been screaming ever since well,
3:11
ever since Trump came back into office,
3:13
I can argue. So, how, you know, critical
3:15
is it to not feed into the frenzy of the
3:17
short-term oil surge? And also, how
3:19
important is this kind of global action
3:23
to be an active investor instead of a
3:25
passive one and allowing someone else
3:27
sort of take control of your portfolio.
3:29
>> Yeah, Maisie, that really is everything
3:31
in in investing that so often we are
3:33
tempted to try and make day-by-day
3:36
investment decisions. But, we know the
3:38
short-term is completely unpredictable
3:40
and really over the the long-term is
3:43
when we're going to see returns in our
3:45
our investments. That doesn't mean we
3:46
shouldn't make any decisions at the
3:48
moment. One of the things that you find
3:49
with crises is that you get some
3:52
collateral damage. Uh, We saw this in
3:56
Brexit most memorably when we woke up
3:58
the morning after Brexit, Japan was down
4:01
very sharply. Japan wasn't impacted by
4:03
Brexit, but it was the one liquid market
4:05
that people could express themselves
4:07
overnight as the poll changed. We could
4:09
have a similar situation now. There are
4:11
pockets of markets around the world that
4:14
we should be looking out for that may
4:15
offer great long-term value, but don't
4:17
expect them to come good over the next
4:19
few days or weeks. All investment
4:22
decisions are essentially long-term
4:24
investment decisions.
4:25
>> And that means more than anything it's
4:27
important to be an active investor
4:28
rather than a passive one in this sort
4:29
of scenario.
4:30
>> Well, the good thing about being a
4:31
passive investor is that you're less
4:33
likely to get drawn into the day-to-day
4:35
minutiae. And passive investments are
4:38
probably the best way to go for for most
4:40
people. Certainly one of the lowest cost
4:41
ways of investing, but that only works
4:44
if you are quite passive. If you want to
4:47
make lots of decisions, if you want to
4:48
take control, then of course
4:51
doing that in an active way, but
4:52
remaining focused on the long term is
4:54
the way to go. The The people that get
4:56
tend to get themselves in most trouble
4:58
are the passive investors that jump in
5:00
and out of markets. That's not what
5:01
passive investment is designed for.
5:03
>> And right now, how does this look for
5:05
investors who may have their hands
5:07
within stocks that are sort of being,
5:08
you know, impacted by this conflict? And
5:11
how does it affect stocks and shares
5:12
ISAs? How does it affect in pensions?
5:13
You know, what what does that look like?
5:14
>> Yeah, well, let's let's start with
5:16
pensions. Again, for for most people,
5:18
unless you're drawing on your pension
5:19
now, you've got a a way to go before
5:22
that money is is relevant. So, again,
5:24
less important for pensions. For people
5:26
with ISAs, then they'll they can access
5:28
that money whenever they want to. There
5:29
is a danger that they take flight at
5:32
this moment. That's a perfectly natural
5:34
behavioral response, but it's normally
5:37
the wrong decision because if you sell
5:39
your investments now, you typically
5:41
don't buy back in at the right time, and
5:43
that can cost you enormously in the long
5:46
run. And so, ISAs can be quite dangerous
5:48
because you can access the money. So,
5:51
really important that people resist that
5:53
temptation. Look for opportunities,
5:55
particularly opportunities to buy when
5:56
prices are low, but at the same time,
6:00
don't go thinking well, you can take the
6:01
money out now and and put it back in.
6:03
It's possible with ISAs, of course, but
6:05
probably not a good idea.
6:07
>> At times like this, investors often talk
6:09
about the so-called taco trade. That's
6:12
the Trump always chickens out at Credem.
6:14
Where uh know, when the when we see a
6:16
major policy decision by Trump, there's
6:18
some wild market moves, then after a
6:20
couple of weeks, Trump kind of pulls
6:22
back and and decides to sort of U-turn
6:24
on some of his policy decisions. Is
6:27
there any expectation that we'll see
6:28
something like this that after a couple
6:29
of weeks, Trump will scale back what he
6:32
intends to do in Iran and then markets
6:34
will will will start to calm down again?
6:36
>> Well, I'm not a geopolitical analyst,
6:38
but I think what what we saw last week,
6:40
President Trump declaring that the war
6:42
was already won, that's potentially a an
6:45
off-ramp in terms of of of
6:48
de-escalation. And so, people should
6:50
certainly have the the the taco trade in
6:53
their mind, the fact that he does change
6:56
his mind very quickly, we we know that.
6:58
And so, we could see a rapid end, we
7:00
should could see prices recovering, oil
7:02
prices fall again, but that's only one
7:05
possible outcome. The biggest mistake we
7:07
make as investors is getting overly
7:09
committed to a particular narrative
7:12
about the future. When making investment
7:13
decisions, always think
7:15
probabilistically. Taco is one outcome,
7:17
let's assign a probability to that. The
7:19
other probability is that this becomes
7:21
another never-ending war that we saw a
7:24
couple of decades ago. And so, you when
7:26
you're thinking about the price of
7:27
assets, you need to try and bear both
7:29
those scenarios and other scenarios in
7:31
your mind rather than getting overly
7:33
attached to one particular outcome.
7:34
>> If we look at the FTSE over the past
7:37
week, it's seen some pretty wild share
7:39
price action. Uh
7:41
you know, companies like airlines seeing
7:43
the sharp sell-off in their in their
7:45
shares.
7:46
Hotel chains not doing very well. On the
7:48
flip side,
7:50
oil companies obviously doing incredibly
7:52
well.
7:53
Mining companies falling.
7:55
How exposed are UK equities relative to
7:59
other other global equities?
8:01
>> Well, that's a really good question,
8:02
Simon. So, so yes, you're right. The The
8:04
UK market, firstly, it's important to
8:06
remember that the largest stocks in the
8:09
in the market normally are known as the
8:11
FTSE 100. They're sort of the largest
8:12
hundred-ish stocks. They're not really
8:15
UK companies. They're companies based in
8:16
the UK, but they have global earnings.
8:19
And so, that's one of the reasons
8:21
they're both susceptible to what's
8:24
happening in the Middle East, but also
8:25
beneficiaries in some cases, as you
8:27
said, energy companies to to higher
8:29
prices as well. So, you are dealing with
8:31
a basket of global companies. But you're
8:33
also dealing with a group of companies
8:36
where their value is made up of the
8:39
earnings that they'll accrue far into
8:42
the future.
8:43
And so, whatever happens over the coming
8:46
days, weeks, or months really has a
8:49
limited impact on the real value of
8:51
those businesses. So, if you see these
8:53
prices fall sharply, particularly below
8:56
a reasonable estimate of what their fair
8:59
value, their true value of these
9:00
businesses are, then they could provide
9:02
a a great opportunity. So, rather than
9:04
thinking about how exposed the UK is,
9:07
think about it as a potential source of
9:08
great opportunity if there's this
9:11
pervading sense of negativity and that
9:13
drives prices far too low.
9:15
>> Lastly, a lot of commentators are
9:17
comparing the events of the the past
9:18
week to what we saw in 2022 with the the
9:22
Russian invasion of Ukraine, which
9:24
triggered a a huge surge in oil and gas
9:26
prices. How strong do you see those
9:29
those parallels?
9:30
>> Well, they they are strong and they're
9:31
strong in a in a particular dimension,
9:34
which is that if you're worried about
9:36
inflation and if you're worried about
9:38
low growth, uh, then what tends to
9:41
happen is that equity prices, share
9:42
prices, and bond prices fall at the same
9:45
time. That's what we saw in 2022. It's
9:47
one of the reasons why people who were
9:49
holding cautious portfolios typically
9:52
did worse in '22 than those that were
9:54
holding more adventurous portfolios
9:56
portfolios with more equities in them.
9:57
And so, we're seeing a parallel of that,
9:59
but again, that doesn't mean it's going
10:01
to happen over the course of a of a
10:03
year. We're just seeing the starting
10:05
signs. That's one possible outcome.
10:07
There's plenty of evidence to support
10:10
that that was coming out the US last
10:12
week with jobs numbers there. And we'll
10:15
see some concerns around inflation
10:16
probably this week. But just remember,
10:18
all of those outcomes really are just
10:21
one possible scenario. That actually
10:24
2022 is is not currently a guaranteed
10:28
outcome. There are plenty of other
10:30
things that can happen, particularly if
10:31
the president changes mind as we
10:33
mentioned earlier. So, yes, parallels,
10:35
but we shouldn't build our portfolios
10:37
around that one particular outcome.
10:39
>> Well, thanks ever so much for coming in,
10:41
Dan, and do keep in touch with all of
10:42
the latest market developments that
10:44
we're seeing and the fallout from the
10:46
Iran war over at cityam.com.
News