Retirement Strategy: The 4% Rule & Guardrails for Financial Independence
May 2, 2025
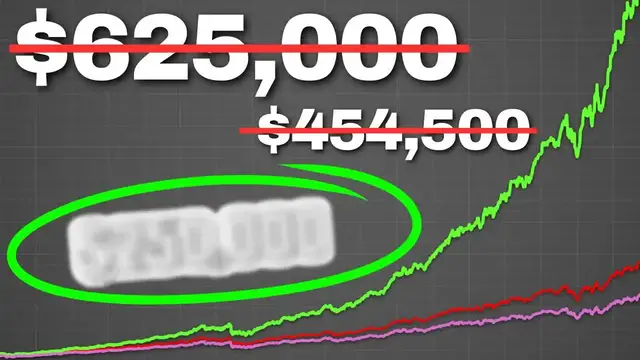
In this video we are talking about which Retirement Income Strategy works best for the Average Joe Investor. Retirement Income Strategies like the 4% Rule OR The Guyton-Klinger Strategy work well BUT require significant levels of capital. In this video I back test the strategy of selling covered calls on the S&P 500 Index (SPY ETF).
----------------------------------------------------------------------------------------
JOIN THE PATREON COMMUNITY!
WANT ACCESS TO ALL OF MY SPREADSHEETS I USE ON THE CHANNEL ALONG WITH THE MONTHLY DIVIDEND STOCK SPREADSHEET AND INSTANT AWARENESS OF CHANGES TO MY PORTFOLIO? JOIN THE PATREON COMMUNITY!
----------------------------------------------------------------------------------------
You can also Work with Joe 1 ON 1!
Want to increase your option selling knowledge and get started!
----------------------------------------------------------------------------------------
Partner With Me - [email protected]
----------------------------------------------------------------------------------------
Need a GREAT Dividend Tracker for your portfolio? Here is what I use and it is EXCELLENT:
The Dividend Tracker:
----------------------------------------------------------------------------------------
Overview of Retirement Income Strategies
Retirement income strategies are designed to help retirees convert their savings and assets into a reliable stream of income that will last throughout their retirement years. There are several approaches, each with distinct advantages and disadvantages, and many retirees use a combination to balance income stability, growth, and flexibility.
Common Retirement Income Strategies
1. Interest and Dividends Only
This method involves living off the income generated from investments such as bonds, CDs, and dividend-paying stocks, without touching the principal.
Pros: Minimal risk to principal (especially with insured CDs and government bonds); principal is returned at maturity for fixed-income products.
Cons: Income can be unpredictable due to fluctuating interest rates and dividends; heavy reliance on fixed income can expose you to inflation risk; may not keep up with rising costs.
2. Systematic Withdrawals (Total Return Approach)
Retirees make regular withdrawals from their investment portfolio, drawing from both principal and investment earnings.
Pros: Flexibility and potential for portfolio growth; can automate withdrawals for simplicity.
Cons: Requires active management; risk of depleting savings if withdrawals are too high or markets perform poorly.
3. Guaranteed Income Strategies
These rely on sources like Social Security, pensions, and annuities to provide a steady, predictable income.
Pros: Reliable income not affected by market volatility; peace of mind regarding longevity risk.
Cons: Typically lower overall returns; may involve fees and loss of liquidity; less flexibility.
4. The Bucket Approach
Assets are divided into separate "buckets" based on the time horizon for when the funds will be needed:
Short-term (cash, CDs for immediate needs)
Intermediate-term (bonds for the next 3–10 years)
Long-term (stocks for growth over 10+ years)
Pros: Balances liquidity, risk, and growth; helps manage market downturns by not forcing sales of long-term investments during volatility.
Cons: Requires careful management and periodic rebalancing; still subject to market risk.
5. The Four Box Strategy
Expenses are categorized as essential or discretionary, and matched with appropriate income sources (guaranteed income for essentials, variable sources for discretionary).
Pros: Ensures essential expenses are covered by stable income; allows flexibility for other spending.
Cons: Requires ongoing planning and management.
6. The 4% Rule
Withdraw 4% of your retirement savings in the first year, adjusting for inflation in subsequent years.
7. Dividend Income
Focuses on investing in dividend-paying stocks to generate a steady income stream.
8. Real Estate Income
Income is generated from rental properties or real estate investment trusts (REITs).
9. Annuities
Insurance products that provide guaranteed income for life or a set period.
10. Tax-Efficient Withdrawal Strategies
Withdraw from taxable, tax-deferred, and tax-free accounts in a tax-conscious order to minimize taxes and maximize after-tax income.
Summary
There is no one-size-fits-all approach to generating retirement income. The best strategy-or combination of strategies-depends on your risk tolerance, income needs, asset levels, and personal preferences. A diversified plan that balances stability, growth, and flexibility can provide peace of mind and help ensure your savings last throughout retirement
Show More Show Less